Tracing Authorization Sequences Linking Merchant Profiles to Portable Subscription Platforms
Written by Drew Schmid · Sep 19, 2026
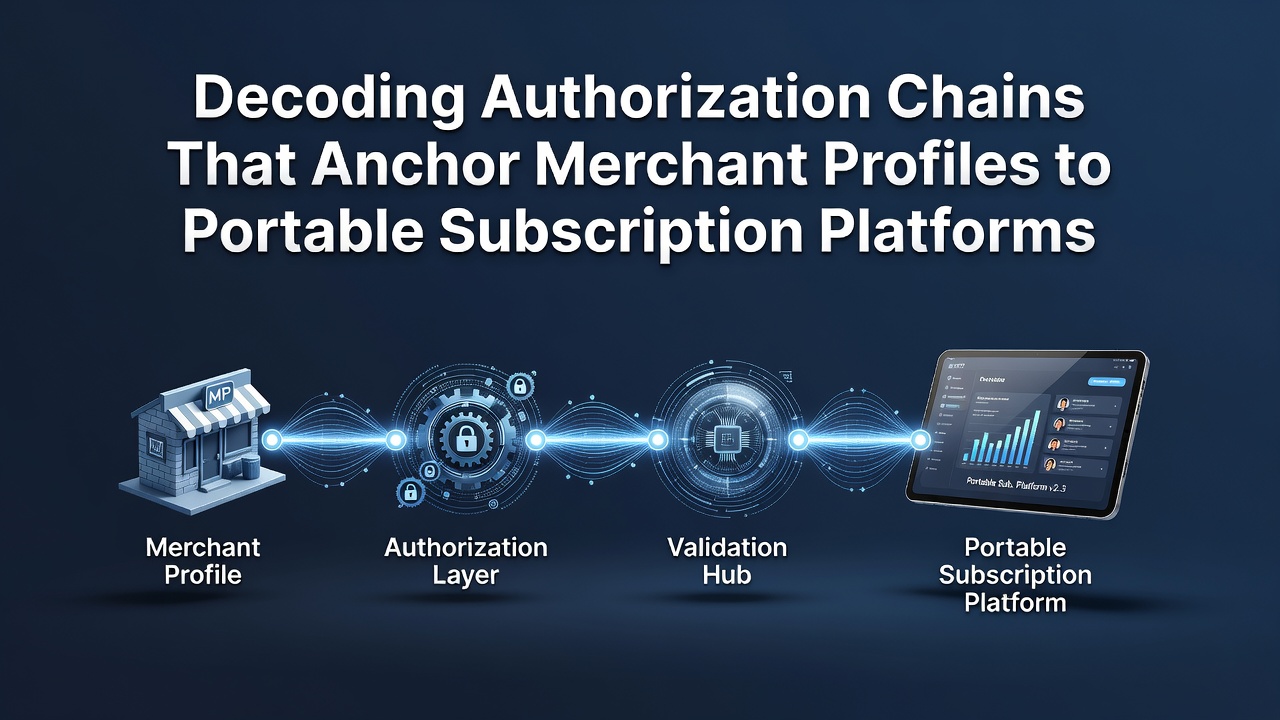
Tracing Authorization Sequences Linking Merchant Profiles to Portable Subscription Platforms
Authorization sequences form the backbone that ties merchant profiles directly to portable subscription platforms, creating stable pathways for recurring transactions across mobile retail channels, and observers note that these structures rely on layered verification steps to maintain consistency in billing cycles. Data from payment networks shows that each chain begins with profile validation at the merchant level before extending through device-specific tokens that authorize ongoing charges on portable hardware, while industry reports indicate this process integrates multiple security layers to prevent disruptions in service renewals.
Core Elements of Merchant Profile Anchoring
Merchant profiles serve as the foundational records that store account details, verification credentials, and settlement preferences, and researchers have found these profiles connect to portable platforms through encrypted authorization tokens that link directly to subscription management systems. In September 2026 figures from the European Central Bank revealed growth in mobile subscription volumes that depended on precise profile anchoring to handle increased transaction loads without interruptions, whereas studies from the Bank of Canada highlighted how these anchors reduce processing errors by aligning merchant data with device identifiers early in the sequence.
Verification Layers in Portable Environments
Portable subscription platforms operate through wireless networks that require real-time authorization checks, and experts observe that chains extend from initial merchant setup to device registration by incorporating dynamic keys that update with each billing cycle. This setup ensures that subscription renewals on mobile devices reference the anchored profile for approval, while data indicates that failures in any link within the chain can halt the entire flow until resolved through secondary verification protocols.
Sequence Breakdown Across Mobile Channels
The process unfolds in distinct stages where the merchant profile undergoes initial authentication before authorization requests route to the portable platform for subscription confirmation, and analysts note that intermediate nodes in the chain perform token validation to confirm account status and available credit lines. But here's the thing: each step builds on the previous one with cumulative data checks that prevent mismatched billing attempts, and evidence from payment processing audits shows these sequences handle thousands of concurrent mobile transactions daily across retail networks.
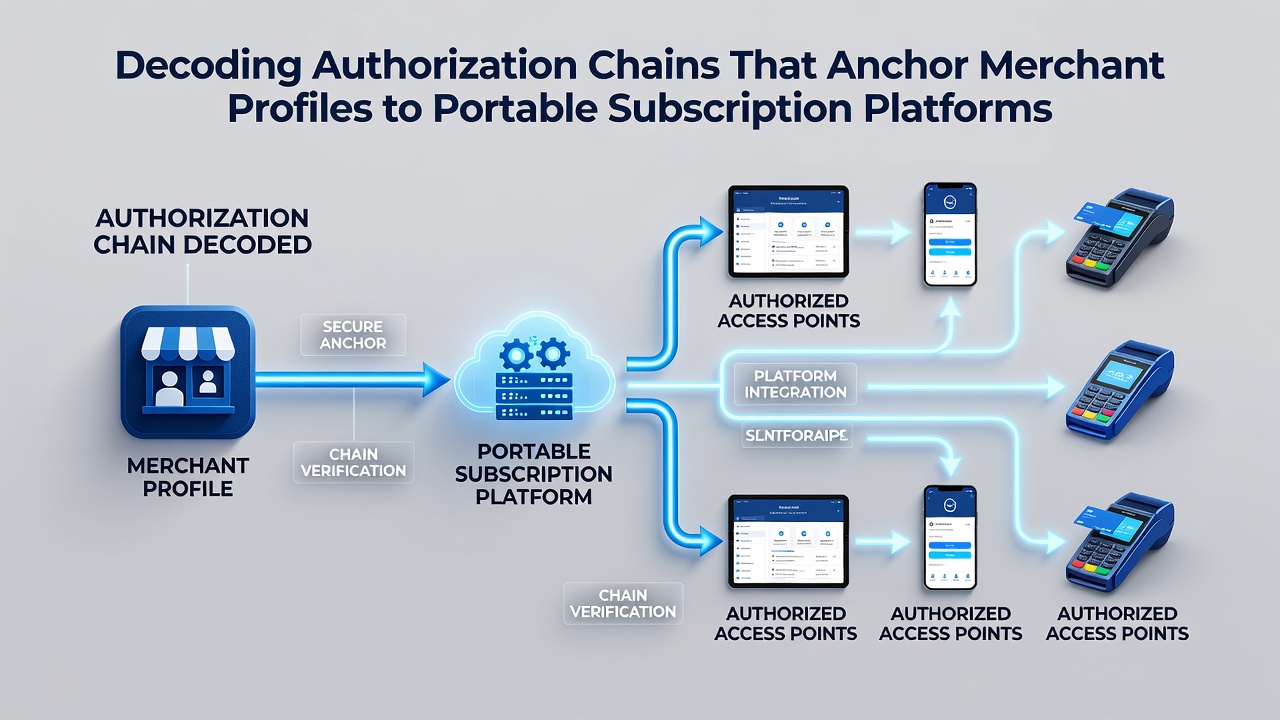
Once the chain reaches the portable device layer, subscription platforms issue renewal prompts that pull from the anchored profile to execute charges, and those who've examined these systems know the integration relies on standardized protocols to maintain uninterrupted service across different device types. What's interesting is how foreign exchange elements factor into international chains, where currency conversions occur within the authorization sequence to keep billing consistent for users on portable platforms regardless of location.
Integration Points with Subscription Management
Subscription platforms on portable devices draw authorization from merchant profiles through secure gateways that enforce profile-specific rules, and research from academic sources at institutions like the University of Melbourne indicates these connections support automated renewals by embedding renewal parameters directly into the authorization chain. Observers have documented cases where profile updates at the merchant end propagate instantly across the chain to adjust subscription terms on mobile endpoints, preventing billing discrepancies that might otherwise arise from outdated data.
Security Mechanisms Within the Chains
Encryption and multi-factor checks form critical components that protect the links between profiles and platforms, while PCI Security Standards Council guidelines emphasize the need for continuous monitoring to detect anomalies in authorization flows. Data shows that chains incorporating these mechanisms experience fewer interruptions in mobile subscription services, and case examples from retail operators demonstrate how coordinated updates across the sequence maintain operational stability even during peak usage periods.
Conclusion
Authorization chains that anchor merchant profiles to portable subscription platforms continue to evolve with advancements in mobile technology, and ongoing developments in verification protocols support reliable recurring billing across wireless retail environments. Those monitoring these systems report sustained improvements in transaction success rates tied to refined chain structures, while geographic variations in implementation reflect adaptations to local regulatory requirements from bodies such as the Reserve Bank of Australia.